Personal Finance Made Easy: Build Better Money Habits
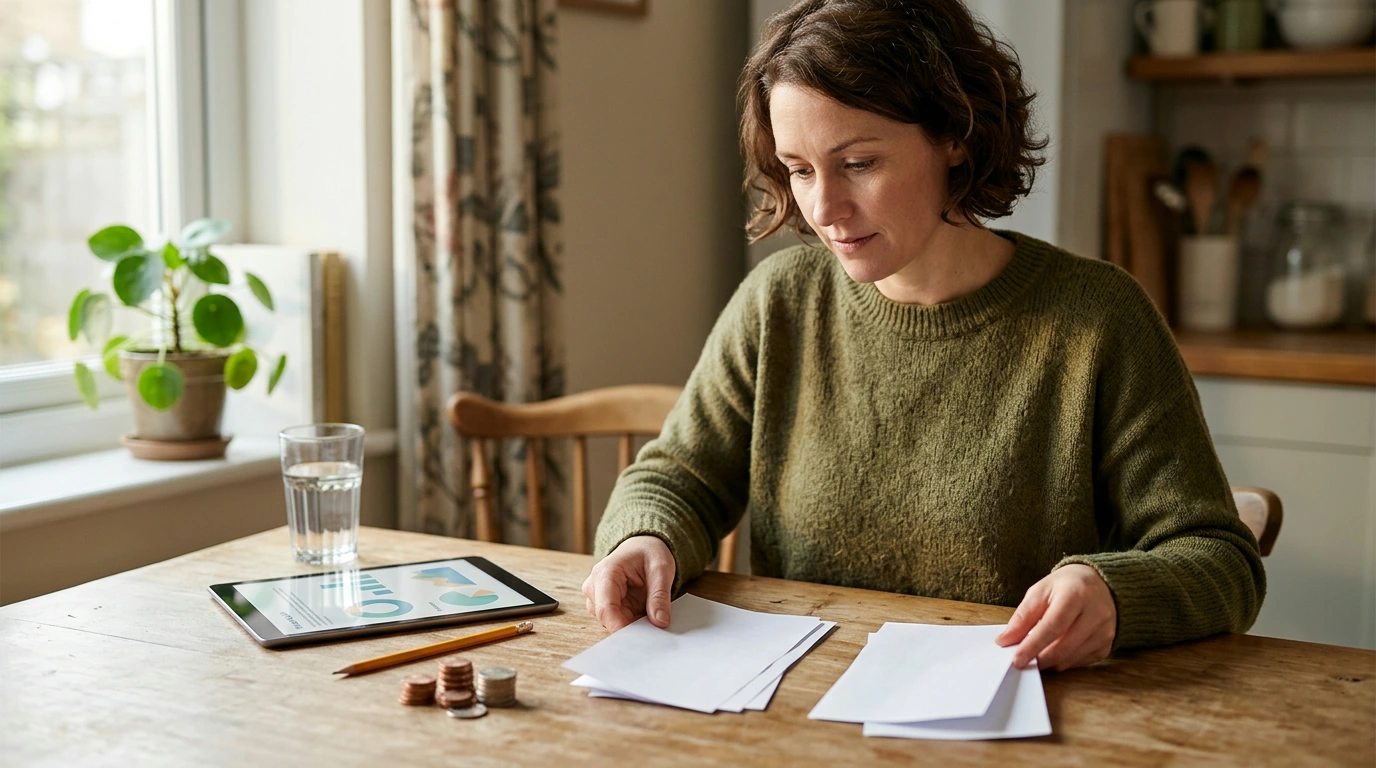
Better money habits often start with a few small questions: What comes in, what needs to go out, and what would you like your money to do next? You don’t need a perfect spreadsheet or a detailed investment strategy to begin. You need a clear starting point and a plan you can revisit.
Our team offers Personal Finance Made Easy as a practical introduction to budgeting, saving, debt management, and investing. Use it alongside your own numbers and priorities to choose manageable next steps. Progress will look different for everyone, and no guide can promise a particular financial result.
Start With a Clear Picture of Your Money
Begin by listing your take-home income and the bills you need to cover. Include housing, utilities, groceries, transportation, insurance, and required debt payments. If your income changes from month to month, look back over several months to understand its range rather than relying on your best month.
Next, compare that list with recent bank and credit card transactions. You may spot expenses you forgot, annual bills that need advance planning, or spending that no longer matches your priorities. This exercise is about gathering information, not judging past choices.
Our Personal Finance Made Easy Ebook brings the core topics together in one introductory guide. It is currently listed at $20.99. You can use it as a starting point for organizing a personal money plan, then explore individual topics in more depth as your needs change.
Build a Budget You Can Revisit
A budget is a plan for using the money available to you, not a test you pass or fail. Try grouping expenses into essentials, flexible spending, savings, and debt payments. Required minimum debt payments belong in your plan even if you also choose to make extra payments.
Start with amounts you can realistically maintain. If your income falls short of necessary expenses, focus on the most pressing bills and consider contacting creditors or service providers to discuss your options. When income or expenses change, adjust the plan rather than treating the original numbers as fixed.
The table below is an illustrative check-in, not an allocation required by the ebook. Use the questions to identify one area that deserves attention.
| Area | Question to ask | Possible next step |
|---|---|---|
| Spending | What must be paid each month? | List essential bills and due dates. |
| Saving | What expense could catch me off guard? | Set a manageable emergency savings goal. |
| Debt | Which balances need attention? | List balances, rates, and minimum payments. |
| Investing | What am I saving for long term? | Learn about risk before choosing an investment. |
A brief monthly review can help you catch changes before they become surprises. The Consumer Financial Protection Bureau’s Your Money, Your Goals resources also offer tools for examining income, bills, and financial priorities.
Give Saving and Debt a Place in the Plan
Unexpected expenses can disrupt even a carefully planned month. Setting aside an affordable amount for emergencies can give you a buffer for costs such as a car repair or an urgent trip. A modest goal is a valid place to start; you can revisit the amount as your circumstances allow.
For debt, list each balance, interest rate, and minimum payment. Keep making the required minimum payments, then consider how to use any extra money available. One approach is to put extra payments toward the highest-interest balance first, which can reduce interest costs. Another is to target the smallest balance first, which may give you an earlier sense of progress.
Neither approach settles the question of how much to save at the same time. The balance depends on your income, essential bills, existing savings, interest rates, and other obligations. If you’re struggling to keep up, getting individualized help from a qualified financial counselor may be useful.
Approach Investing With Confidence and Care
Investing can be part of planning for a long-term goal, but it involves risk, including the possible loss of money. Before choosing an investment, consider when you might need the money and how much uncertainty you can comfortably accept.
Learn how diversification can spread exposure across different investments, while recognizing that it does not eliminate risk. Compare fees, too: costs can affect what you keep over time. Investor.gov’s introduction to investing is a useful place to explore these concepts.
Our ebook provides general financial education, not personalized investment advice. For a decision tailored to your situation, consider speaking with a qualified financial professional.
Make Your Next Money Move
Choose one action you can complete this week: track your expenses, list your debt balances, or set a small savings goal. Put a date on your calendar to review what you learn and decide what comes next.
If staying on task is a challenge, our Finally Focused workbook offers a separate focus-building resource. For the money fundamentals, explore Personal Finance Made Easy in our shop and start with the topic that matters most to you.
FAQ
Who is Personal Finance Made Easy for?
It is an ebook for readers seeking an introduction to budgeting, saving, investing, and debt management.
Should I save money or pay off debt first?
Your priorities depend on your circumstances. Consider essential bills, minimum debt payments, emergency savings, and interest rates when deciding how to use available money.
Does investing guarantee financial freedom?
No. Investing involves risk, including the possible loss of money, and outcomes depend on market performance and your personal circumstances.


Leave a comment